

Revolut: Spend, Save, Trade
by Revolut Ltd
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 50.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I installed Revolut: Spend, Save, Trade to see whether it could handle the ordinary money tasks that usually end up scattered across a bank app, a card wallet, and a separate currency or investing service. My starting point was simple: receive or add money, decide where it should go, spend from it, and keep an eye on the result without turning a quick payment into an administrative project. That is the promise behind Revolut’s “change the way you money” idea, but the useful question is whether the app makes that workflow clearer in real life.
My overall impression is that this is a broad finance app rather than a narrowly focused banking tool. It brings spending, saving and trading into one place, which can be convenient when your financial life crosses currencies or when you want a single view of everyday activity. At the same time, that breadth means there are more choices to understand than in a traditional bank app. I found it most appealing for people who like managing money from their phone and are willing to check the details before confirming an action.
From money coming in to a usable daily balance
I found the most useful way to approach the opening balance is to decide its job before moving money around: everyday spending, a planned reserve, or something else. That small pause makes the next steps easier to judge and helps keep available cash distinct from money I intend to leave alone. From there, the practical question is how quickly the app’s connected tools feel during a busy day.
Choosing the right starting point
The first decision is not really about the interface; it is about what you want Revolut to replace. If you only need a basic account for local payments, your existing bank may already do that with less explanation. Revolut becomes more interesting when you want spending and saving tools together, need to think about more than one currency, or prefer a modern mobile workflow over a branch-centered relationship.
The app is developed by Revolut Ltd and is listed as a free finance app for everyone. It has been available since June 2015, and its scale is easy to understand from the store presence: it has passed fifty million installs and holds a 4.5 average from roughly 4.1 million ratings. Those figures do not tell me whether every feature suits every person, but they do show that this is an established product rather than a small experiment.
Setup is also where I would advise slowing down. A finance app deserves more attention than a casual utility because the choices you make affect where money is held and how you use it. I would begin by deciding which account is for routine spending, which money should remain untouched, and whether trading is genuinely part of my plan. Treating every visible option as something I should activate is the quickest way to make the app feel busier than it needs to be.
A practical everyday workflow
Imagine I am preparing for a week away. I want a clear amount for meals and transport, a separate reserve for unexpected costs, and a way to avoid mixing those funds with money intended for longer-term goals. In Revolut, I would start by getting the usable balance in place, then separate the spending decision from the saving decision instead of paying directly from one undifferentiated pot.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That separation is one of the app’s more useful habits. Before I tap a card or approve a transfer, I can ask which portion of my money is meant for today. This sounds obvious, but the visual convenience of a single finance app can encourage impulsive movement between purposes. My tip is to create a simple personal rule: money for immediate bills stays available, money for a planned goal stays out of the everyday path, and trading money is never confused with either.
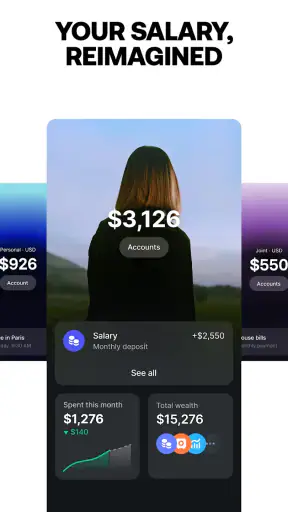
The spending side is strongest when I use it as a live control panel rather than merely a digital card. After a purchase, I can review the transaction while the context is still fresh. That makes it easier to notice whether a payment belongs to the trip budget, a recurring household cost, or an unplanned purchase. The benefit is not just seeing a balance; it is connecting each transaction with the decision that caused it.
For a normal weekday, the workflow is equally straightforward. I might use the app to check whether a subscription has gone through, review recent card activity, and confirm that the remaining balance still matches my plan. I would not rely on memory when the app can show the trail. This is especially helpful for people who use several payment methods and otherwise discover spending only when the monthly statement arrives.
Saving without losing sight of the purpose
The saving part works best when I give it a job. “Save more” is too vague to guide daily choices, while “keep money for a summer trip” or “build a cushion for annual bills” gives the balance meaning. Revolut’s combined design makes it natural to move from spending awareness to a saving decision, but the discipline still comes from the user. The app can organize money; it cannot decide what is genuinely affordable.
I would also keep a distinction between money that is reserved for a near-term goal and money that I can tolerate exposing to market movement. That distinction matters because the app places saving and trading close enough together that a curious user may move from one to the other without considering the different risks. The smooth handoff is convenient, but it should not be mistaken for financial advice.
A useful workflow is to review spending first, save second, and only then consider trading. Doing it in that order prevents an attractive market opportunity from taking priority over rent, bills, or a planned purchase. It also gives me a clearer answer to the question many finance apps leave vague: how much money can I actually afford to put at risk?
Where trading fits, and where it does not
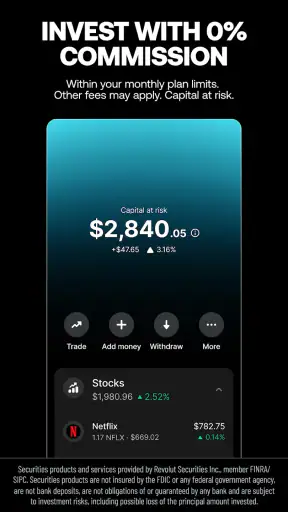
The trading tools may appeal to someone who wants access to investing inside the same app used for daily money. I can see the attraction of avoiding another login and another balance screen. For a beginner, the convenience may make it easier to start learning how markets work. For an experienced investor, the value depends on whether the available tools, instruments and information match a more demanding strategy.
I would not use the trading area as an extension of my spending account. That is the central trade-off. Keeping everything together reduces friction, but it also makes the boundary between cash management and investment decisions less visible. A sensible workflow is to decide the amount outside the app first, transfer only that amount for the intended purpose, and avoid treating a market balance as emergency cash.
Another non-obvious point is the emotional effect of seeing financial actions in one place. A payment feels immediate, saving feels constructive, and trading can feel exciting; placing them side by side may encourage frequent checking or quick switching. I found the app more useful when I used it to execute a plan rather than to generate a new financial decision every time I opened it.
Handoffs between balances, payments and decisions
The real test is what happens between sections. A finance workflow rarely ends when money is added. I need to move from an incoming balance to a spending plan, from a purchase to a record, or from a goal to a reserved amount. Revolut’s main strength is that these handoffs happen within one mobile environment, so I do not have to reconstruct the story across several unrelated services.
That convenience has a cost: I must pay attention to which balance or function I am using before confirming anything. A quick tap can have a different meaning depending on whether I am spending, moving money toward savings, or entering the trading area. My practical advice is to pause at the confirmation stage and read the destination, currency and amount rather than assuming the app has inferred my intention.
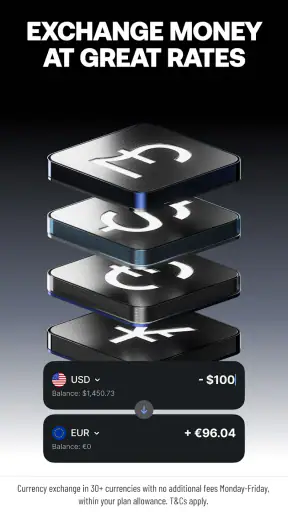
Currency handling is another reason someone might choose this app over a conventional local bank interface. If I travel or receive money connected to another currency, having those concerns near everyday spending can reduce mental overhead. Still, I would compare the displayed terms and final amount before completing a conversion or payment. “Convenient” does not automatically mean “cheapest,” and the right comparison depends on the transaction and the alternatives available to me.
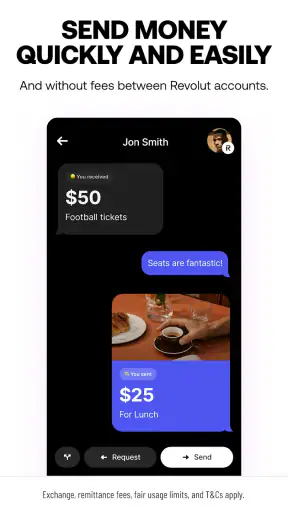
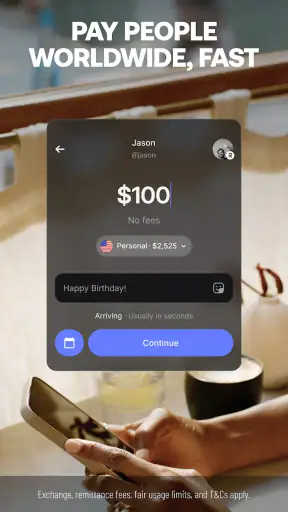
The handoff to an external person or business is where expectations should remain realistic. Revolut can make the preparation and tracking of a payment feel neatly contained, but the recipient’s bank, the payment route and the currency involved can still affect the experience. I would keep confirmation details until the other side acknowledges receipt, especially for an important bill or time-sensitive transfer.
What the finished result looks like
When the workflow goes well, I finish with three things: a spending balance I understand, savings attached to a purpose, and a separate view of any money I have chosen to trade. That is a better outcome than simply having many features. The app earns its place when it helps me answer, quickly, “What can I spend, what am I protecting, and what am I deliberately putting at risk?”
For a traveler, the result can be a cleaner daily routine: check the available spending money, make a purchase, review the transaction, and keep the reserve untouched. For a freelancer or someone paid through different channels, the value may be the ability to see personal money decisions in one place. For a cautious saver, the result is less about advanced functionality and more about making a goal visible enough to avoid accidentally spending it.
I also like that the app can serve different levels of involvement. Someone may use only its spending and saving side, while another person explores trading later. That gradual approach is preferable to assuming every user needs the full product immediately. The app is broad, but I do not have to make every part central to my routine.
Where the workflow breaks down
The first friction is complexity. A traditional bank app often has a narrower purpose: show the account, display payments, and let me move money. Revolut adds more financial paths, which can be powerful but can also make a simple task feel surrounded by choices. If I want an uncomplicated account and rarely travel, save, or invest through my phone, the extra breadth may not justify changing habits.
The second issue is concentration. Putting spending, saving and trading together is convenient, but it can blur risk. A user who is not comfortable with investing may feel nudged toward exploring it simply because it is nearby. I would skip the trading section entirely until I understand the difference between money needed soon and money I can leave exposed to market changes.
There is also a human limitation that no interface removes: financial records need checking. I would not assume that a clean dashboard means every transaction is correct or every payment has reached its destination. Reviewing activity, keeping important confirmations, and checking the final amount before a conversion are small habits that protect the convenience the app is designed to provide.
Another reason to choose a different option is support preference. If I want face-to-face help, a long-established local bank may feel more reassuring. If I need specialized investment research, a dedicated brokerage may be a better fit. If my needs are limited to budgeting, a focused budgeting app could offer less distraction. Revolut is strongest for the person who values one mobile hub, not for someone who wants every financial service optimized independently.
Who should use it
I would recommend Revolut to a mobile-first user who wants spending, saving and trading available from the same finance app, especially when daily money decisions involve travel, multiple currencies or several financial goals. It is also a good candidate for someone who likes reviewing transactions frequently and prefers active control over waiting for a monthly statement.
I would be more cautious about recommending it to a person who dislikes managing settings, wants only a basic current account, or may confuse investment money with emergency funds. The app can support a careful workflow, but its convenience makes it important to bring your own boundaries. It is not a substitute for deciding how much risk, complexity and monitoring you actually want.
My final take after using the complete flow
Revolut: Spend, Save, Trade succeeds when I use it as a connected financial workspace: money arrives, I assign it a purpose, I spend from the right balance, I review what happened, and I keep longer-term decisions separate from daily purchases. That complete flow is more valuable than any single feature because it reduces the number of places where I need to reconstruct my financial life.
The app is free, carries an Everyone content rating, and its current Android version is 10.144.1 with Android 9 as the minimum operating system. Those details make it approachable for a wide range of phone users, while the large install base and substantial rating history suggest a mature mainstream choice. My recommendation is still conditional: start with the spending and saving workflow, learn where each action leads, and treat trading as a separate responsibility rather than an automatic next step.
In the end, I would choose Revolut when convenience across money tasks matters more to me than having a narrowly focused banking experience. I would skip it when simplicity, local support or specialized investing tools matter more. Used with clear boundaries, it gives everyday money a coherent path from incoming funds to a visible outcome. Used without those boundaries, its smooth handoffs can make financial decisions feel easier than they really are.
Pros
- Easy-to-use interface for tracking spending and managing accounts
- Supports multiple currencies for convenient international payments
- Instant spending notifications help monitor transactions in real time
- Virtual and disposable cards add extra security for online purchases
- Offers budgeting tools, savings features, and investment options in one app
Cons
- Some features and benefits depend on your plan or country of residence
- Exchange limits and fair-use rules may apply on free accounts
- Cash withdrawals can incur fees after monthly limits are exceeded
- Customer support is mainly handled through in-app chat
- Trading and crypto services involve risks and may include additional fees
FAQs for Revolut: Spend, Save, Trade
What is Revolut: Spend, Save, Trade, and what can I use it for?
Revolut is a digital banking and financial services app that combines everyday spending, money transfers, savings tools, budgeting features, and investment options in one place. Depending on your country and plan, you may receive a virtual or physical card, exchange currencies, send money internationally, buy selected stocks or cryptocurrencies, and manage subscriptions. Available features, limits, fees, and regulatory protections vary by region.
Is Revolut safe to use for storing money and making payments?
Revolut uses security features such as passcode protection, biometric login, transaction notifications, card freezing, and additional verification for certain activities. However, it is still important to protect your phone and account credentials and to report suspicious activity quickly. The exact legal structure, deposit protection, and safeguarding arrangements depend on the Revolut entity serving you and the country where your account is registered.
Are there fees for using Revolut, exchanging currencies, or withdrawing cash?
Revolut offers different subscription tiers, including a free plan and paid options, but fees and allowances depend on your location and membership. Currency exchange may be subject to fair-use limits, weekend markups, or other charges. Cash withdrawals can also have monthly limits and ATM-related fees. Before using a feature, check the in-app pricing page because rates and conditions may change.
Can I use Revolut to invest in stocks or cryptocurrency?
In supported countries, Revolut may provide access to selected stocks, exchange-traded products, or cryptocurrencies directly through the app. Investment availability, minimum amounts, trading hours, spreads, commissions, and custody arrangements differ by region and account type. Investments can lose value, and cryptocurrency prices can be especially volatile. Review the relevant risk information and product terms before committing money.
What documents are required to open a Revolut account?
To create an account, you generally need a supported phone number, an email address, personal information, and a valid government-issued identity document. Revolut may also request a selfie or video verification and additional information about your address, tax residency, or source of funds. Approval is not guaranteed, and requirements can vary depending on your nationality, location, regulatory checks, and the services you want to access.
Read About Revolut: Spend, Save, Trade in Your Language

Revolut: Spend, Save, Trade
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via feedback@revolut.com, visit https://www.revolut.com/, or review their https://www.revolut.com/legal/privacy/.










